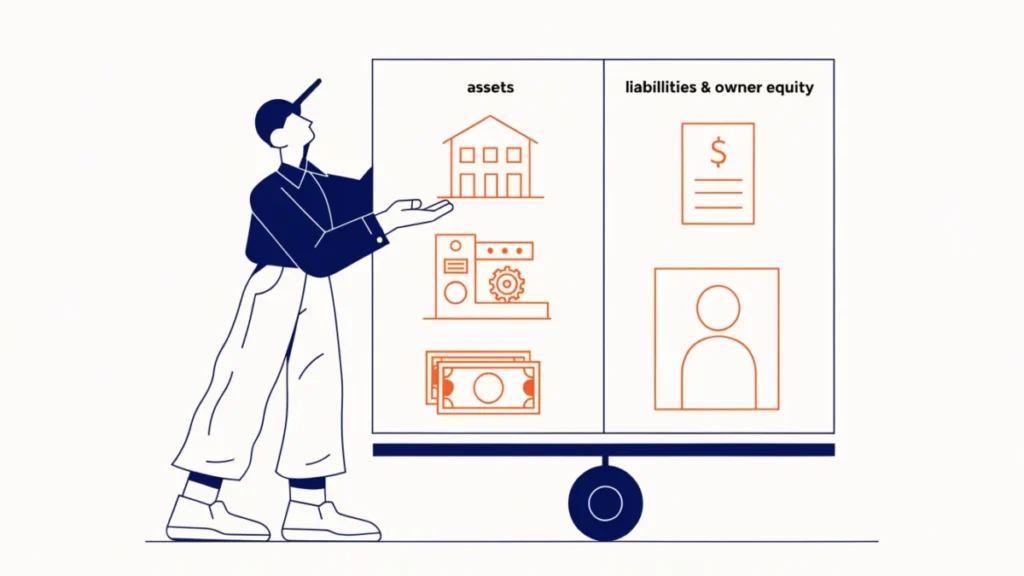
A balance sheet shows what a business owns (assets) and owes (liabilities and equity) on a given date. Under Schedule III of the Companies Act 2013, Indian companies use a vertical format: Equity and Liabilities (shareholders’ funds, non-current liabilities, current liabilities) on top and Assets (non-current and current) below. Both totals must match because Assets = Equity + Liabilities.
A balance sheet is a snapshot of what a business owns and owes on one specific date, usually 31 March for Indian companies. It rests on one equation that never changes:
Assets = Equity + Liabilities
If a company has ₹24 lakh of assets, someone financed them: either the owners (equity) or outsiders (liabilities). The balance sheet shows exactly who. In India, companies must follow the vertical format set out in Schedule III of the Companies Act, 2013, which we walk through below with a worked example.
Why Do We Need a Balance Sheet?
- Owners see what their investment is worth on paper and how much the business has kept back as reserves.
- Banks check whether the company can repay: they look at debt against equity and current assets against current liabilities before sanctioning a loan.
- Investors judge financial strength. Two companies with the same profit can carry very different levels of debt.
- Suppliers decide how much credit to give.
- Regulators and tax authorities rely on it for filings with the Registrar of Companies and for audits.
It is one of the main financial statements a business prepares, alongside the profit and loss account and the cash flow statement.
Read more: Elements of cost explained with a worked cost sheet example.
Balance Sheet Format (Schedule III, Companies Act 2013)
Schedule III uses a vertical format: equity and liabilities on top, assets below. Here is the structure with a worked example for a small manufacturing company, ABC Pvt Ltd, as at 31 March 2026.
Read more: Format of balance of payments.
| Particulars | Amount (₹) |
|---|---|
| I. EQUITY AND LIABILITIES | |
| 1. Shareholders’ funds | |
| (a) Share capital | 10,00,000 |
| (b) Reserves and surplus | 4,00,000 |
| 2. Non-current liabilities | |
| (a) Long-term borrowings (term loan) | 6,00,000 |
| (b) Deferred tax liabilities (net) | 0 |
| (c) Long-term provisions | 0 |
| 3. Current liabilities | |
| (a) Short-term borrowings | 0 |
| (b) Trade payables | 3,00,000 |
| (c) Other current liabilities | 0 |
| (d) Short-term provisions (tax) | 1,00,000 |
| TOTAL | 24,00,000 |
| II. ASSETS | |
| 1. Non-current assets | |
| (a) Property, plant and equipment | 12,00,000 |
| (b) Non-current investments | 2,00,000 |
| 2. Current assets | |
| (a) Inventories | 4,00,000 |
| (b) Trade receivables | 3,50,000 |
| (c) Cash and cash equivalents | 2,00,000 |
| (d) Short-term loans and advances | 50,000 |
| TOTAL | 24,00,000 |
Both totals match at ₹24 lakh. If they do not, an entry is missing or wrong.
Assets Explained
Non-Current Assets
Assets the business expects to use for more than 12 months. Property, plant and equipment covers land, buildings, machinery, vehicles and furniture, shown at cost less depreciation. Intangible assets include software, patents and trademarks. Capital work-in-progress is a factory still under construction. Non-current investments are shares or bonds held for the long term.
Current Assets
Assets expected to turn into cash within 12 months or one operating cycle: inventories (raw material, work-in-progress, finished goods), trade receivables (customers who bought on credit), cash and bank balances, and short-term loans and advances such as advance payments to suppliers.
Equity and Liabilities Explained
Shareholders’ Funds (Owners’ Equity)
Share capital is the money shareholders put in. Reserves and surplus are profits the company has kept rather than paid out as dividends, plus items such as securities premium. For a sole trader or partnership this section is simply called capital.
Non-Current Liabilities
Obligations due after 12 months: term loans from banks, debentures, deferred tax liabilities (tax that will be payable later because of timing differences between book and tax depreciation) and long-term provisions such as gratuity.
Current Liabilities
Obligations due within 12 months: trade payables (suppliers yet to be paid), short-term bank borrowings such as cash credit, the current portion of long-term loans, outstanding expenses and provisions for tax.
What the Balance Sheet Tells You
Two quick ratios from the ABC example show how to read it.
| Ratio | Formula | ABC Pvt Ltd | What it means |
|---|---|---|---|
| Current ratio | Current assets ÷ Current liabilities | 10,00,000 ÷ 4,00,000 = 2.5 | ₹2.50 of short-term assets for every ₹1 due within a year; comfortable |
| Debt-equity ratio | Long-term debt ÷ Shareholders’ funds | 6,00,000 ÷ 14,00,000 = 0.43 | Owners fund more than twice as much as lenders; low financial risk |
Banks in India commonly look for a current ratio of at least 1.33 for working capital loans, so ABC would pass easily.
Balance Sheet Formula
Total Assets = Shareholders’ Funds + Non-Current Liabilities + Current Liabilities
Rearranged, Equity = Assets − Liabilities. That is the book value belonging to the owners. For ABC, ₹24 lakh of assets minus ₹10 lakh of liabilities leaves ₹14 lakh of equity, which matches share capital plus reserves.