Deferred revenue expenditure is a large revenue expense whose benefit lasts several years, such as a launch advertising campaign or preliminary expenses, so it is written off over those years instead of in one go. Note that current standards (AS 26 and Ind AS 38) require most such costs to be expensed immediately, so the deferred treatment is now mainly an exam concept.
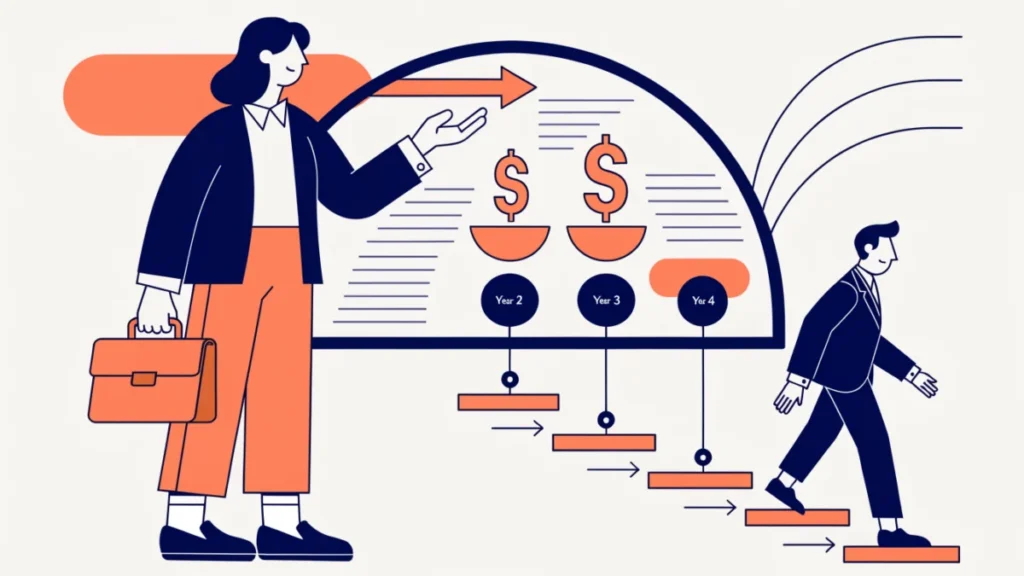
Deferred revenue expenditure is a large expense of a revenue nature whose benefit is expected to last for several years. Instead of charging the whole amount to the profit and loss account in the year it is spent, it is spread (written off) over the years that benefit, and the unwritten balance is carried forward.
What is Deferred Revenue Expenditure?
It sits between capital and revenue expenditure. Like revenue expenditure, it does not create an asset the business can sell. Like capital expenditure, its benefit lasts beyond one year. So it is written off gradually, for example over three to five years.
Classic examples:
- Heavy advertising to launch a new product
- Preliminary expenses of forming a company
- Brokerage and underwriting commission on issue of shares or debentures
- Discount on issue of debentures
- Cost of shifting the business to more convenient premises
- Exceptionally heavy repairs that extend benefit for several years
Example: a company spends ₹3,00,000 on a launch campaign expected to benefit three years. It charges ₹1,00,000 to profit and loss each year, and at the end of year one ₹2,00,000 remains to be written off.
Important: What Current Accounting Standards Say
The idea of deferred revenue expenditure is still taught in commerce courses, but current standards largely do not allow it. Under AS 26 and Ind AS 38 (intangible assets), spending on advertising, preliminary expenses, research and similar items must be charged to profit and loss in the year incurred, because it does not create an identifiable asset. Discount and issue costs on debentures are written off against securities premium or spread over the debt’s life as part of the effective interest. Schedule III of the Companies Act, 2013 no longer has a heading for “miscellaneous expenditure not written off”. Use the deferred treatment for exam answers that ask for it, and immediate expensing in real company accounts.
Practice Questions with Answers
Q1. Legal expenses incurred in raising a loan.
Classic answer: deferred revenue expenditure, since no asset is created but the loan benefits several years. Under Ind AS 109 these costs are treated as transaction costs and spread over the loan through the effective interest rate.
Q2. Cost of experimenting with a chemical product that did not succeed.
Write it off immediately as a revenue loss. A failed experiment creates no future benefit, and research costs are expensed under AS 26 in any case.
Q3. ₹5,000 spent on dismantling, removing and reinstalling plant at a more convenient location, and ₹3,000 on moving stock to the new site.
Classic answer: the ₹8,000 is deferred revenue expenditure because the benefit of the better site lasts for years. Under current standards (AS 10 / Ind AS 16), relocation costs are not added to the asset’s cost and are charged to profit and loss.
Q4. ₹20,000 spent on heavy advertising to introduce a new product.
Classic answer: deferred revenue expenditure, written off over the years that benefit. Under AS 26 / Ind AS 38 advertising is expensed in the year incurred.
Capital Expenditure vs Deferred Revenue Expenditure
| Basis | Capital expenditure | Deferred revenue expenditure |
|---|---|---|
| Asset created | Yes, a tangible or intangible asset | No asset |
| Can be sold | Yes, the asset can be sold for cash | No, nothing to sell |
| Treatment | Shown as an asset and depreciated | Written off over a few years (classic view) |
| Example | Purchase of machinery | Launch advertising campaign |
Related reading: capital vs revenue expenditure, capital vs revenue payments and capital vs revenue losses.